The 20% flat-rate option at a glance
Key takeaway. Since 1 January 2025, a landlord whose tenant is a company can swap the 10% or 15% withholding for a final 20% withholding on gross rent. No 40% deduction, no year-end adjustment, no annual return for those rents. The option only lowers your tax if your other income already puts you in the 34% or 37% brackets.
Before 2025, withholding on rent was only an advance. Each year the landlord declared the rent, the DGI recomputed the tax on the progressive scale after the 40% deduction, then refunded or claimed the difference. The 2025 Finance Law added a second route: a single 20% rate withheld by the tenant, which settles the tax. This guide covers who can opt, how to do it, and above all when the option costs more than it saves.
The legal basis: what the 2025 Finance Law changed
The option rests on four articles of the Moroccan General Tax Code (CGI), amended by article 8 of the 2025 Finance Law. Article 64-IV creates the right to opt. Article 73-II-F-12° sets the final rate at 20%. Article 86-6° exempts rent taxed at that rate from the annual return. Article 160 bis requires the tenant to withhold 20% once it receives a copy of your option.
The withholding base is the gross taxable rental income defined in article 64-I: gross rent, plus the owner's expenses charged to the tenant, minus the charges the owner bears on the tenant's behalf. The DGI's circular no. 736 states that this withholding applies without the 40% deduction and without the 40,000 MAD threshold below which a company tenant normally withholds nothing.
The rules apply to rent collected from 1 January 2025. Landlords who do not opt see no change: non-final withholding of 10% below 120,000 MAD of annual rent and 15% from 120,000 MAD, then an adjustment on the scale in the return filed before 1 March. Those thresholds are detailed in our 2026 RAS scale on rent.
Who can opt, and for which rents
The option is open to individuals whose rent is subject to withholding. That means rent paid by a company, a public body, an association, or a professional taxed under the real net income (RNR) or simplified (RNS) regime. An office let to an SARL, a shop let to a pharmacy, a flat rented by a company to house a manager: all of these rents qualify.
Rent paid by a private individual stays outside the scheme. It is not subject to withholding, so it cannot be covered by the option: you declare it every year and it follows the scale after the 40% deduction. A landlord who lets one flat to a family and one office to a company runs two regimes side by side.
The option is all or nothing: it covers every property you let to tenants who withhold. You cannot keep the scale for one unit and take the 20% for another. A single request covers the lot, and every tenant concerned must receive a copy.
How to opt, step by step
Step 1: file the option request electronically with the DGI, using the official form. The administration issues a receipt. Step 2: give a copy of that receipt to each tenant who withholds, at least 30 days before the rent due date of the month following your request. Step 3: the option takes effect from the month after the copy is handed over. The tenant then withholds 20% instead of 10% or 15%.
A sample timeline: you file on 2 October 2026 and hand the receipt the same day to your tenant, whose rent is due on the 5th of each month. The 30-day notice before the 5 November rent is met, and November's rent is withheld at 20%. Rent from January to October 2026, withheld at 10% or 15%, must still be declared on the scale before 1 March 2027.
For the whole of 2027 to fall under the 20% rate, your tenants need the copy by the end of November 2026 at the latest. Going back to the scale works the same way: an electronic request against a receipt, then a copy handed to tenants at least 15 days before the next month's rent is due.
The maths: 20% of gross against the scale after the deduction
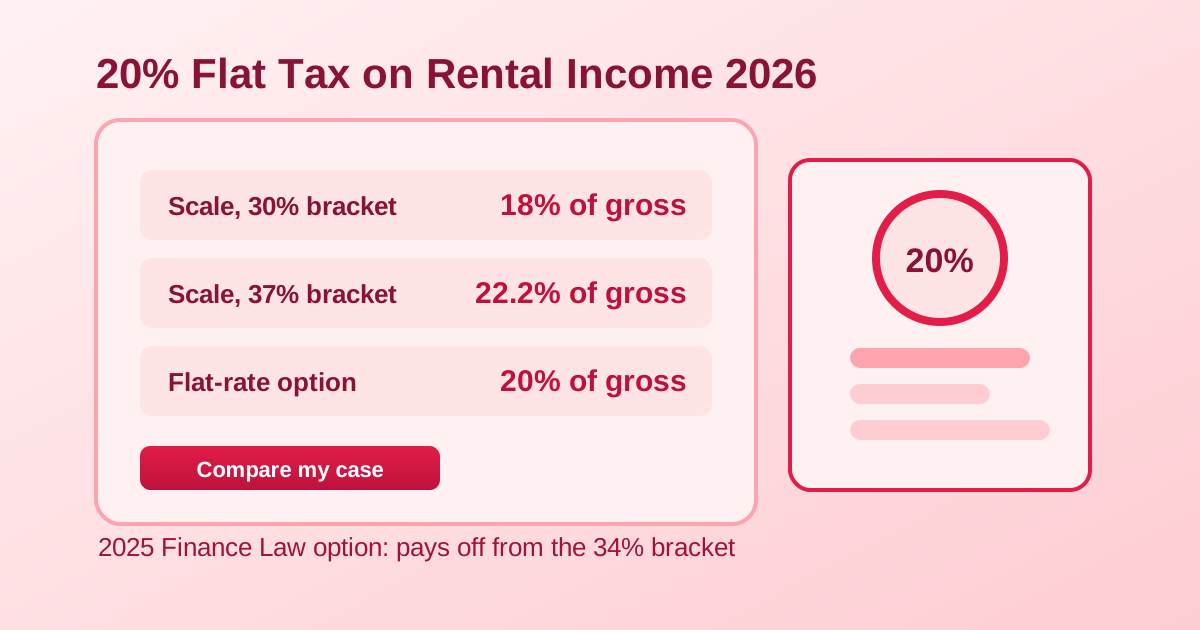
Under the scale, only 60% of gross rent is taxed, after the 40% deduction. Each dirham of rent costs 0.6 times your marginal rate. With the option it costs 0.20 dirham, whatever your income. The break-even point is a marginal rate of 33.3%, since 0.6 × 33.3% = 20%.
| Marginal bracket of your net income | Cost under the scale (% of gross rent) | Flat-rate option | Better choice |
|---|---|---|---|
| 0% (up to 40,000 MAD) | 0% | 20% | Scale |
| 10% (40,001 to 60,000 MAD) | 6% | 20% | Scale |
| 20% (60,001 to 80,000 MAD) | 12% | 20% | Scale |
| 30% (80,001 to 100,000 MAD) | 18% | 20% | Scale |
| 34% (100,001 to 180,000 MAD) | 20.4% | 20% | Option (0.4 point saved) |
| 37% (above 180,000 MAD) | 22.2% | 20% | Option (2.2 points saved) |
The reading is simple: the option only saves money on the share of net rent that lands above 100,000 MAD of net global income. An employee whose net taxable salary already exceeds 180,000 MAD saves 2.2 points on every dirham of rent. A landlord who lives on rent alone almost always pays more with the option. To test your own case on the scale, use the rental tax calculator.
Three worked cases: Casablanca, Marrakech, Tangier
Casablanca, senior manager. Net taxable salary of 240,000 MAD from a single employer. An office floor in Maârif is let for 12,000 MAD a month to an SARL, so 144,000 MAD a year. Under the scale, the rental base is 144,000 × 60% = 86,400 MAD, all taxed at 37%: 31,968 MAD of tax. The SARL has already withheld 15%, or 21,600 MAD, leaving 10,368 MAD to pay on filing. With the option: 144,000 × 20% = 28,800 MAD, withheld at source, with no return. Saving: 3,168 MAD a year.
Marrakech, civil servant. Net taxable income of 90,000 MAD. A flat in Guéliz is let for 6,000 MAD a month to a company that houses an employee there, so 72,000 MAD a year. The 43,200 MAD rental base lifts global income to 133,200 MAD: 10,000 MAD taxed at 30% and 33,200 MAD at 34%, so 14,288 MAD of extra tax. With the option: 14,400 MAD. Gap: 112 MAD in favour of the scale. Here the option only buys less paperwork.
Tangier, investor with no other income. A shop is let for 8,000 MAD a month to a pharmacy run as an SARL, so 96,000 MAD a year. Under the scale: a 57,600 MAD base, of which only 17,600 MAD sits above the 0% bracket, so 1,760 MAD of tax. The 10% withheld during the year (9,600 MAD) gives a refund of 7,840 MAD. With the option: 19,200 MAD, with no refund at all. Extra cost: 17,440 MAD a year.
| Profile | Annual rent | Tax under the scale | 20% option | Difference |
|---|---|---|---|---|
| Casablanca, salary 240,000 MAD | 144,000 MAD | 31,968 MAD | 28,800 MAD | Option saves 3,168 MAD |
| Marrakech, income 90,000 MAD | 72,000 MAD | 14,288 MAD | 14,400 MAD | Scale saves 112 MAD |
| Tangier, no other income | 96,000 MAD | 1,760 MAD | 19,200 MAD | Scale saves 17,440 MAD |
Pitfalls to avoid before opting
Opting on a low income. This is the most expensive mistake, as the Tangier case shows. A retiree or an investor with no salary gets the full benefit of the 0% bracket up to 40,000 MAD of net income and of the 40% deduction. The option removes both. Forgetting the 40,000 MAD threshold. Without the option, a company tenant paying you 3,000 MAD a month (36,000 MAD a year) withholds nothing. With the option, it withholds 7,200 MAD a year.
Losing part of your main-residence interest deduction. Rent taxed at the final rate leaves your global taxable income, which is the base for the 10% cap on deductible mortgage interest under article 28-II. For the Casablanca manager, the cap falls from 32,640 MAD to 24,000 MAD. If they pay 30,000 MAD of interest, they lose 6,000 MAD of deduction, roughly 2,220 MAD of tax. The real saving then drops below 1,000 MAD. The mechanism is explained in our guide to deducting mortgage interest from income tax.
Handing over the receipt late. Until the tenant has the copy in time, it keeps withholding 10% or 15%, and those months must be declared on the scale. Assuming the return disappears. The exemption only covers rent withheld at 20%. Rent from individuals, business income or salaries from several employers must still be declared before 1 March, as set out in our rental income filing guide. Ignoring cash flow. With the option you collect 80% of the rent each month instead of 85% or 90%, and nothing comes back at year end.
Official sources and key points
Key points: the 20% final rate settles the tax on rent paid by a company and removes it from your return. It pays off from a 34% marginal rate, meaning net global income above 100,000 MAD, and it is costly for low incomes. Run the numbers including your main-residence interest deduction, then decide before the end of November to cover the following year.
Useful sources
- Direction Générale des Impôts, official portal
- DGI circular no. 736 on the tax measures of the 2025 Finance Law
- Moroccan General Tax Code, articles 64, 73, 86 and 160 bis
- Rental income tax in Morocco 2026
- The 40% deduction on rental income
- Morocco rental tax calculator
The figures in this guide are indicative and use the IR scale in force in 2026, before family-charge reductions. Your situation depends on all of your income: have your choice checked by a chartered accountant or your local tax office before filing the option request.
Frequently asked questions
- Who can opt for the 20% final rate on rental income in Morocco?
- Individuals whose rent is subject to withholding, meaning rent paid by a legal entity or by a professional under the real or simplified net income regime. Rent paid by private individuals is not covered.
- Do I still need to declare rent taxed at the 20% final rate?
- No. Article 86-6° of the CGI exempts rent actually withheld at 20% from the annual return. Other income, such as rent from individuals or months withheld at 10% or 15% before the option, must still be declared before 1 March.
- From what income level does the 20% option pay off?
- Under the scale, one dirham of rent costs 60% of your marginal rate. The option wins above a 33.3% marginal rate, so in the 34% and 37% brackets, which start at 100,000 MAD of net global income.
- Does the 40,000 MAD threshold apply under the option?
- No. The 20% final withholding applies from the first dirham of rent, with no 40% deduction and without the withholding exemption that otherwise covers annual rent up to 40,000 MAD.
- How do I cancel the option and return to the scale?
- File a cancellation request electronically with the DGI, then hand a copy of the receipt to your tenants at least 15 days before the next month's rent is due. Later rents are withheld again at 10% or 15% and adjusted on the scale.
Use our Morocco rental profitability calculator
Gratuit · Résultats en 2 minutes