Yes, you can deduct your home loan interest from income tax
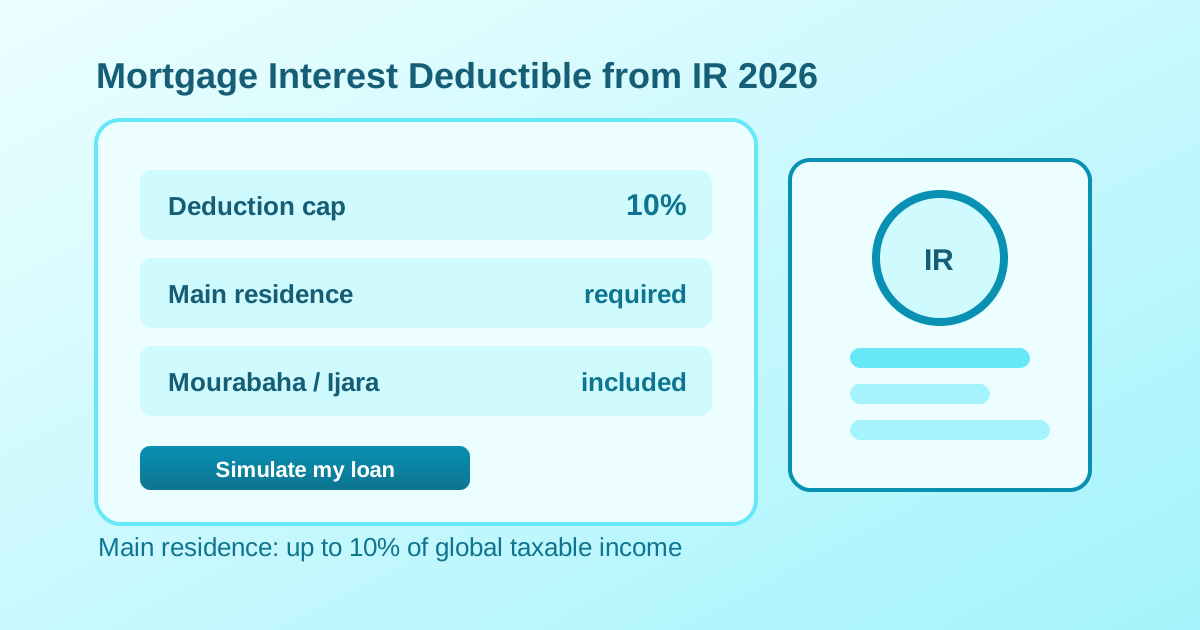
If you took out a loan to buy or build your primary residence in Morocco, you can deduct the interest from your income tax (IR, formerly IGR). Many taxpayers call this an abatement. In reality it is a deduction on your global taxable income, within a 10% limit.
This deduction is separate from the one for rental income. Here it is about your own home, not a property you rent out. This article details the 10% rule, what is deductible, the conditions and a full worked example.
The legal framework: Article 28-II of the General Tax Code
The deduction is provided by Article 28-II of the General Tax Code (CGI). It is for the taxpayer who took out a loan to acquire or build the home they occupy as their primary residence.
The principle: the interest paid during the year, and the loan arrangement fees, are deducted from your global taxable income before the income tax is calculated. By lowering your taxable base, the deduction directly reduces the tax due.
Important point: the deduction is not on the capital repaid, but on the interest portion of your monthly payments. Your bank issues an annual interest certificate each year that separates capital and interest.
The 10% of global taxable income rule
The deduction is capped at 10% of the global taxable income (RGI). If your annual interest exceeds this cap, only the fraction matching 10% of the RGI is deductible, and the rest is lost for the year.
The global taxable income is all of your income subject to income tax (net taxable salary, professional income, property income) after the applicable deductions. The higher your income, the higher the 10% cap.
To frame the impact, here is the 2026 income tax scale:
| Annual income bracket | 2026 income tax rate |
|---|---|
| 0 to 40,000 MAD | 0% |
| 40,001 to 60,000 MAD | 10% |
| 60,001 to 80,000 MAD | 20% |
| 80,001 to 100,000 MAD | 30% |
| 100,001 to 180,000 MAD | 34% |
| Above 180,000 MAD | 37% |
What is deductible: conventional interest and participatory finance
The deduction covers the interest on loans granted by banks, credit institutions and similar bodies. The arrangement fees tied to the loan are also included.
Participatory finance is treated the same way. The advance remuneration agreed in a Mourabaha contract and the rental margin of an Ijara Mountahia Bitamlik contract are deductible under the same conditions and the same 10% of RGI limit. Whether your credit is conventional or participatory, the tax benefit exists.
Watch the no-cumulation rule: this deduction cannot be combined with certain deductions provided by Articles 59-V and 65-II of the CGI. Check your situation if you fall under a specific regime.
Worked example: an employee earning 200,000 MAD
Take an employee whose annual global taxable income is 200,000 MAD. They are repaying a loan for their primary residence and paid 30,000 MAD of interest during the year.
The deduction cap is 10% x 200,000 = 20,000 MAD. Even though they paid 30,000 MAD of interest, only 20,000 MAD is deductible this year.
Their taxable income drops from 200,000 to 180,000 MAD. Since this income band is taxed at the 37% marginal rate, the tax saving reaches about 20,000 x 37% = 7,400 MAD for the year. That is a direct cut to your income tax, not to be overlooked.
To see the interest portion of your monthly payments and the schedule, use our mortgage simulator.
Conditions and documents to provide
First condition: the home must be effectively occupied as a primary residence. The administration requires you to justify this use within 3 years from the date of the occupancy permit.
Second point: keep the annual interest certificate issued by your bank and the amortization schedule. These are the documents that prove the amount of interest paid.
For an employee, the deduction can be applied directly by the employer on the payroll, on presentation of the supporting documents, or recovered through a refund at the annual return. Ask your payroll department.
Do not confuse it with the property income deduction
There are two very different interest deductions in Morocco. The one described here is for your primary residence and offsets your global income, within the 10% limit. The other is for a property you rent out: the loan interest is then deducted from the property income, under its own rules, detailed in our guide to interest deductible from property income.
Special case: for the acquisition of social or economic housing, the treatment can be more favourable, in some cases with deductibility without the 10% cap. Check the conditions that apply to your programme.
Before buying, factor this tax benefit into your financing plan. Our guide to financing a property purchase helps you structure your down payment and your loan.
Official sources and key takeaways
Key takeaways: the interest on a loan for your primary residence is deductible from income tax within the limit of 10% of your global taxable income. Participatory Mourabaha and Ijara financing open the same right. Keep your bank's interest certificate and justify occupation of the home.
Useful sources
- Directorate General of Taxes (DGI): tax.gov.ma
- General Tax Code, Article 28-II
- 2026 income tax scale (finance act)
- Loan interest deductible from property income
- How to finance a property purchase in Morocco
This information is indicative and based on the CGI and the 2026 scale. Your exact situation depends on your income and your regime. Have your calculation validated by a chartered accountant or the DGI.
Frequently asked questions
- What is the cap on home loan interest deduction in Morocco?
- Interest on a loan for the primary residence is deductible from the global taxable income within the limit of 10% of that income. The interest above this cap is not deductible.
- Does the deduction apply to participatory loans (Mourabaha, Ijara)?
- Yes. The advance remuneration of a Mourabaha contract and the rental margin of an Ijara Mountahia Bitamlik contract are deductible under the same conditions and the same 10% of global taxable income limit.
- Does the home have to be my primary residence?
- Yes. The home must be occupied as a primary residence, and the use must be justified within 3 years from the occupancy permit. A property you rent out falls under a different deduction.
- Can the repaid capital be deducted?
- No. Only the interest portion of the monthly payments is deductible, along with the loan arrangement fees. The repaid capital is not part of the deduction. The bank's interest certificate separates the two.
- How do I actually get the deduction?
- On presentation of the interest certificate, the deduction can be applied by the employer on the payroll, or recovered at the annual income return. Keep the amortization schedule as supporting evidence.
Use our Morocco rental profitability calculator
Gratuit · Résultats en 2 minutes