Why the interest rate is the most decisive variable
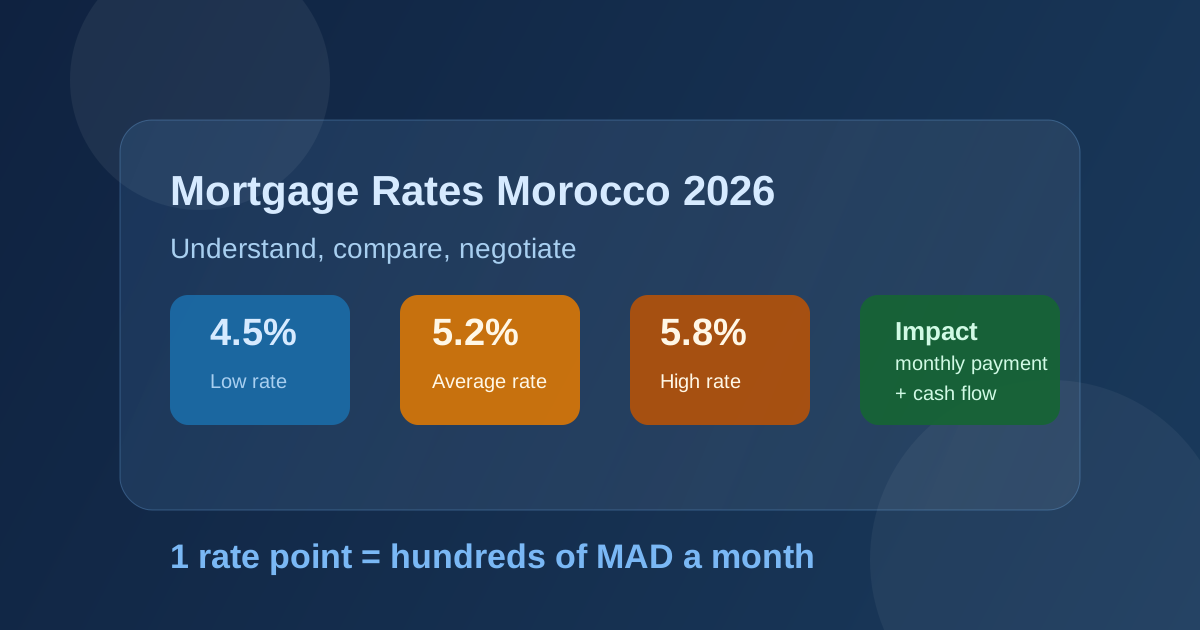
The mortgage interest rate directly determines your monthly payment and, by extension, the real profitability of your investment. A single percentage point difference can add several hundred MAD per month and significantly reduce your annual cash flow. This is why understanding current rate levels is essential before making any financial commitment.
In 2026, mortgage rates in Morocco remain influenced by Bank Al-Maghrib's decisions on its benchmark rate. After the easing cycle of 2024, the market has partially stabilized, but conditions vary by institution and borrower profile. Comparing offers and negotiating actively can make a material difference over the full loan term.
Our mortgage simulator lets you measure the exact impact of each rate scenario on your monthly payment, total interest cost, and the full amortization schedule.
Mortgage rate levels in Morocco in 2026
In 2026, fixed rates for a standard Moroccan mortgage typically range from 4.5% to 5.8% depending on the institution, loan term and borrower profile. Attijariwafa, CIH Bank, Banque Populaire, BMCE Bank of Africa and Societe Generale Maroc are the main players. Variable rates remain less common but may start lower, with the risk of upward revision if the benchmark rate rises.
Subsidized rates, accessible through certain social housing programs or employer-bank agreements, can fall below 4%. These are limited in availability and subject to strict eligibility conditions (income caps, primary residence use). For a standard buy-to-let investment, it is prudent to plan with a rate between 5% and 5.5% to maintain a safety margin in your projections.
Use our mortgage simulator to measure exactly how each rate level impacts your monthly payment and total financing cost.
Fixed vs variable rate: which to choose in 2026?
A fixed rate offers complete predictability. You know your monthly payment for the entire loan term, which simplifies cash flow management and rental income tracking. For an investor seeking stability over a 15-25 year horizon, fixed is generally preferable. The payment will not change even if market conditions shift.
A variable rate can seem attractive if the initial rate is lower. But if the benchmark rate rises, your monthly payment increases and puts profitability under pressure. Model this risk explicitly before choosing: test a scenario where the rate increases by 1 point after 3 years and check whether cash flow remains acceptable. If it does not, fixed is the safer choice.
In our ROI calculator, you can test different rate levels and see the impact on annual cash flow and return on invested equity.
The concrete impact of rates on monthly payments
For a loan of 700,000 MAD over 20 years: at 4.5%, the monthly payment is approximately 4,430 MAD. At 5.5%, it rises to around 4,810 MAD. The difference of 380 MAD per month represents 4,560 MAD per year, a direct hit on annual cash flow. Over 25 years, sensitivity is even greater: an extra half-point can reduce net cash flow by several thousand MAD per year.
On a property rented at 7,000 MAD/month with 1,200 MAD in monthly charges, moving from a 4,430 to a 4,810 MAD monthly payment shifts cash flow from +1,370 to +990 MAD per month. That is often the difference between a comfortable project and one that requires very tight management. Check the mortgage monthly payment guide for detailed scenario analysis.
Negotiating your rate: available levers
The rate is not a fixed given. Moroccan banks generally leave room for negotiation, especially for strong applications. The main levers are: a high down payment (20-30% or more), demonstrable income stability (CDI seniority, regular income track record), an existing banking relationship, and salary domiciliation with the lending bank.
Putting banks in competition is also highly effective. Present two or three offers and ask each institution to match or improve. This can yield a saving of 0.2 to 0.5 percentage points, which is significant over a long term. A mortgage broker can help if you are short on time or your file is complex. Always compare APRs (not just nominal rates) to get the full picture of financing cost including insurance and fees.
Loan term and rate: finding the optimal balance
A longer term reduces the monthly payment but increases total interest cost. On a 700,000 MAD loan at 5%: over 15 years, the monthly payment is ~5,531 MAD with 295,000 MAD in total interest. Over 25 years, the payment drops to ~4,094 MAD but total interest reaches 528,000 MAD, 79% more. The right term depends on your rental income and repayment capacity.
In buy-to-let investing, the goal is often to maximize positive monthly cash flow, which argues for a longer term. But if rent comfortably covers the payment, shortening the term reduces total financing cost. Model several term/rate combinations in our ROI calculator to identify the structure that maximizes your net profitability.
Checklist before signing a mortgage offer
Mortgage checklist Morocco 2026
- Compare at least 3 offers from different banks.
- Check the full APR (rate + insurance + arrangement fees).
- Simulate a 1-point rate increase if choosing a variable rate.
- Confirm the monthly payment is covered by rent in a conservative scenario.
- Include acquisition costs in your total equity calculation (~7% of price).
- Verify your final ROI in the mortgage simulator.
A good mortgage is not just the cheapest upfront. It is one that remains manageable throughout the project, leaves acceptable cash flow, and can absorb a few months of vacancy without putting the project under strain.
FAQ + resources on Morocco mortgages 2026
- What is the average rate in 2026? Between 4.5% and 5.8% for a standard loan, depending on profile and bank.
- Does the benchmark rate affect my mortgage? Yes, indirectly. A cut by Bank Al-Maghrib can feed through to lower bank rates over the following months.
- Should I wait for a further rate cut? Not necessarily. Waiting can mean missing a good buying opportunity. Better to model current scenarios in our calculator.
- How do I simulate my monthly payment? Directly in our mortgage simulator.
Useful references
Use our Morocco rental profitability calculator
Gratuit · Résultats en 2 minutes