Rental income in 2026: who must file
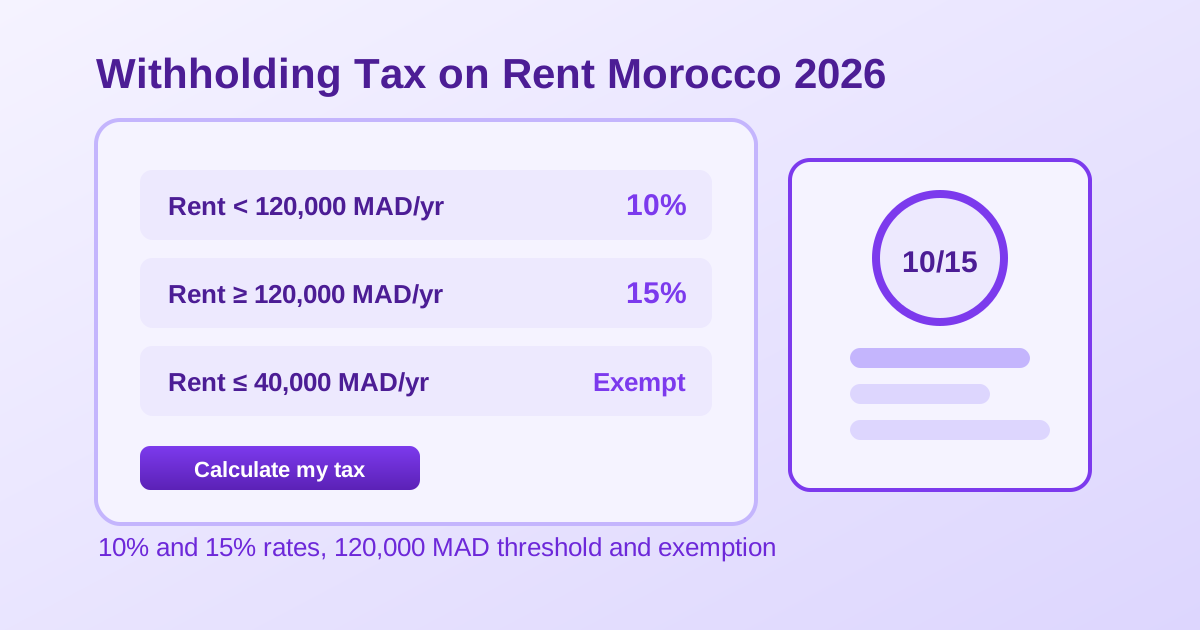
Rental income covers rent from built and unbuilt property let unfurnished by individuals, plus certain deemed rental values. If you collect rent in Morocco, you must report it every year in your global income tax return, even when annual rent stays under 30,000 MAD (income then exempt), and even when your tenant has already applied a withholding tax.
The return is not a mere formality: it is what triggers the crediting of amounts already withheld and, very often, a tax refund in your favour. Not filing means both risking surcharges and abandoning a tax credit.
The legal framework: articles 82 and 173-I of the CGI, 1 March deadline
Since the 2023 Finance Law, the former dedicated rental income return (article 82 ter of the CGI) is repealed: rents are included in the annual global income return under article 82 of the CGI, with spontaneous payment of the tax due under article 173-I. Filing and payment must happen before 1 March of the year following collection.
For 2025 income, the DGI set the practical deadline at 2 March 2026, since 1 March fell on a Sunday. Do not confuse this with the business income deadline (before 1 May): an employee or retiree collecting rent falls under the 1 March deadline for rental income.
Taxable base: the 40% deduction and the 30,000 MAD exemption
The taxable base is the gross rent collected during the year, reduced by the flat 40% deduction for built property. No other expense is deductible under this regime: works, building charges, insurance and agency fees are deemed covered by the deduction. Example: a flat let at 6,000 MAD/month brings 72,000 MAD gross, a taxable base of 72,000 × 60% = 43,200 MAD.
Rental income whose gross annual amount does not exceed 30,000 MAD is exempt from income tax for residential lettings. The exemption does not remove the filing duty: the rent must appear in the return, and the administration applies the exemption itself. Full rules in our rental income tax guide.
The 2026 income tax scale applied to net rental income
| Net global income bracket | 2026 IR rate |
|---|---|
| Up to 40,000 MAD | 0% |
| 40,001 to 60,000 MAD | 10% |
| 60,001 to 80,000 MAD | 20% |
| 80,001 to 100,000 MAD | 30% |
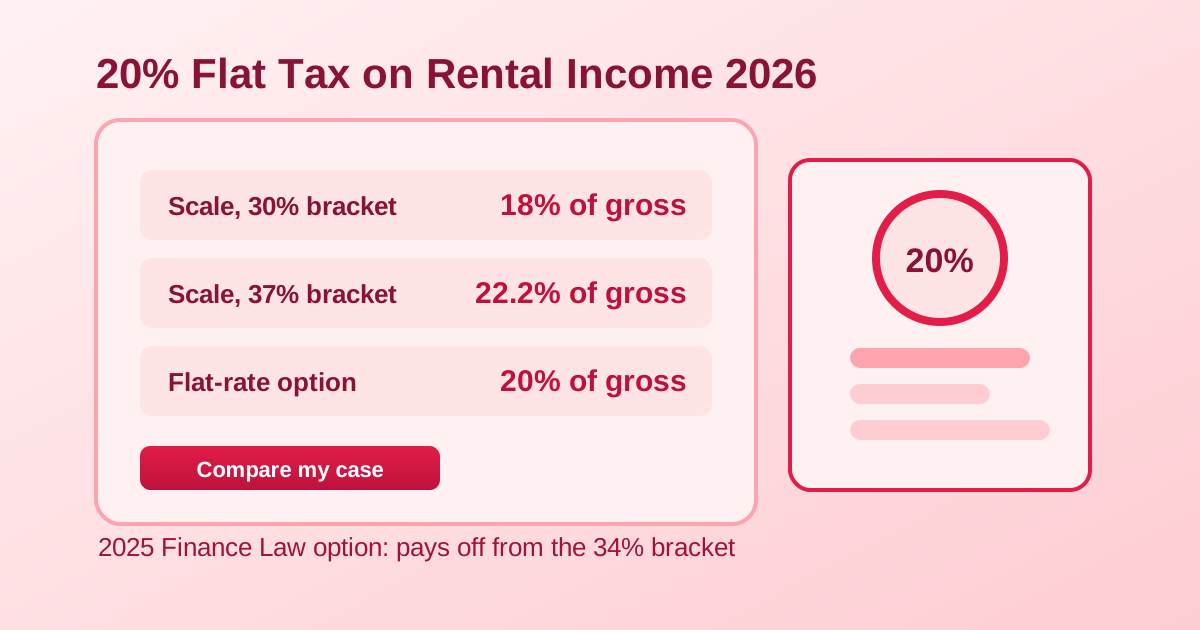
| 100,001 to 180,000 MAD | 34% |
| Above 180,000 MAD | 37% |
Back to the 43,200 MAD base: tax due is 10% of the 3,200 MAD above 40,000, so 320 MAD for the year. With 96,000 MAD of gross rent (8,000 MAD/month), the base reaches 57,600 MAD and the tax 1,760 MAD. Test your own figures in the rental tax calculator, which applies the deduction and the scale automatically.
Filing online on Simpl-IR: the step-by-step process
Step 1: create your account on the DGI's Simpl-IR portal with your tax identifier (enrolment in the e-services is done online, validated by your tax office). Step 2: fill in the global income return and its rental income annex: tenants' identity and tax IDs, property addresses, rent collected, withholding suffered.
Step 3: validate the return and proceed to online payment of the tax due (bank card or direct debit). Step 4: download and keep the filing receipt and payment slip. Also keep lease contracts, rent receipts and RAS certificates: in an audit, these documents substantiate every declared amount.
Case study: employee in Rabat with a flat let at 6,500 MAD/month
A Rabat employee lets a flat in Agdal for 6,500 MAD/month, 78,000 MAD/year. Rental taxable base: 78,000 × 60% = 46,800 MAD. If this rent were his only income, tax would be 10% × 6,800 = 680 MAD, an effective rate of 0.9% of gross.
But the scale applies to global income: net taxable salary and rental income add up. For a salary already in the 34% bracket, the 46,800 MAD rental base bears 34%, around 15,912 MAD. The real taxation of a rental investment depends on your other income: always simulate the full project, rent, loan and tax, in the profitability simulator before buying.
Late filing, penalties and catching up
Late filing triggers surcharges of 5% to 20% depending on the delay and how the situation is regularised, plus late-payment penalties and interest on the tax due. The administration now cross-checks registered lease contracts, withholdings reported by professional tenants and owners' returns: a missing return is easily detected.
If you skipped previous years, a voluntary regularisation before any audit sharply limits the bill. File the missing returns and contact your tax office. Amounts in this guide remain indicative: have your file validated by a tax advisor or chartered accountant.
Official sources and related guides
The official global income filing guide and the Simpl e-services are published by the DGI. Check them before each filing season, as deadlines and forms can change with the Finance Law.
Useful sources
Frequently asked questions
- What is the deadline for filing rental income in 2026?
- Before 1 March 2026 for rent collected in 2025. As 1 March fell on a Sunday, the DGI set 2 March 2026 as the last day for filing and payment.
- Must I file if my annual rent is below 30,000 MAD?
- Yes. Residential rental income is exempt under that threshold, but the annual global income return remains mandatory.
- My tenant already withholds tax at source, do I still need to file?
- Yes. The RAS is only an advance: the return credits it against your actual tax and lets you recover any surplus.
- Can I deduct actual expenses (works, building charges, insurance)?
- No. Under the rental income regime the flat 40% deduction is deemed to cover all expenses. No further deduction is allowed.
- How do I pay the tax due on rental income?
- By online payment on Simpl-IR (bank card or direct debit) when filing the return, before 1 March.
Use our Morocco rental profitability calculator
Gratuit · Résultats en 2 minutes