Your monthly payment drives cash flow
A rental investment financed by a mortgage stands or falls on the monthly payment. This number determines whether rent covers financing or you must subsidize the property. Small changes in rate or term can transform the entire deal.
Calculating payments accurately lets you model multiple scenarios: different rates, larger down payments, or longer terms. This flexibility is essential in Morocco, where conditions vary by bank and borrower profile.
Our rental ROI calculator uses the standard amortization formula to provide a fast, reliable estimate.
The basic formula in plain language
The payment depends on three inputs: principal (P), monthly rate (r), and number of payments (n). The formula spreads principal and interest across the loan term.
For investors, the key is the cash flow effect. You can borrow more, but if the payment exceeds net rent, your ROI collapses. Adjust down payment, rate, or term to keep the payment sustainable.
Start with a baseline in our ROI tool and observe how changes affect cash-on-cash performance.
Rate and term impact
A higher rate raises the payment even if the term stays the same. A 1-point increase can add hundreds of MAD per month. Longer terms reduce the payment but increase total interest paid.
The goal is a payment that fits the rental income while keeping the total cost reasonable. Investors often adjust the down payment to reduce the principal.
Use our calculator to test several combinations and find the best tradeoff between monthly effort and total cost.
Financing changes your ROI
Leverage boosts ROI when rent covers most of the payment. But if the payment is heavy, negative cash flow reduces your ability to reinvest.
Measure annual net cash flow: (rent - payment - expenses) x 12. Divide by your invested cash to get cash-on-cash ROI, which is more useful than gross yield.
Our rental ROI calculator automates this calculation so you can compare structures quickly.
Simple example
Assume a 1,000,000 MAD purchase, 200,000 MAD down payment, 70,000 MAD acquisition fees, and a 870,000 MAD loan at 4.5% over 20 years. The payment is about 5,500 MAD per month. If net rent after expenses is 7,000 MAD, cash flow is positive.
If net rent is 5,000 MAD, cash flow is negative by 500 MAD monthly. That is 6,000 MAD per year, which must be weighed against potential appreciation.
Plug these numbers into our calculator to see the ROI impact and refine assumptions.
Practical tips before signing
Before signing
- Compare multiple rate offers.
- Negotiate bank fees.
- Check the cost of loan insurance.
- Keep a safety buffer for expenses and vacancy.
Do not choose a project solely based on the lowest rate. Flexibility of repayment and bank stability matter too.
Run multiple scenarios in our ROI calculator before signing a mortgage.
Down payment: finding the right balance
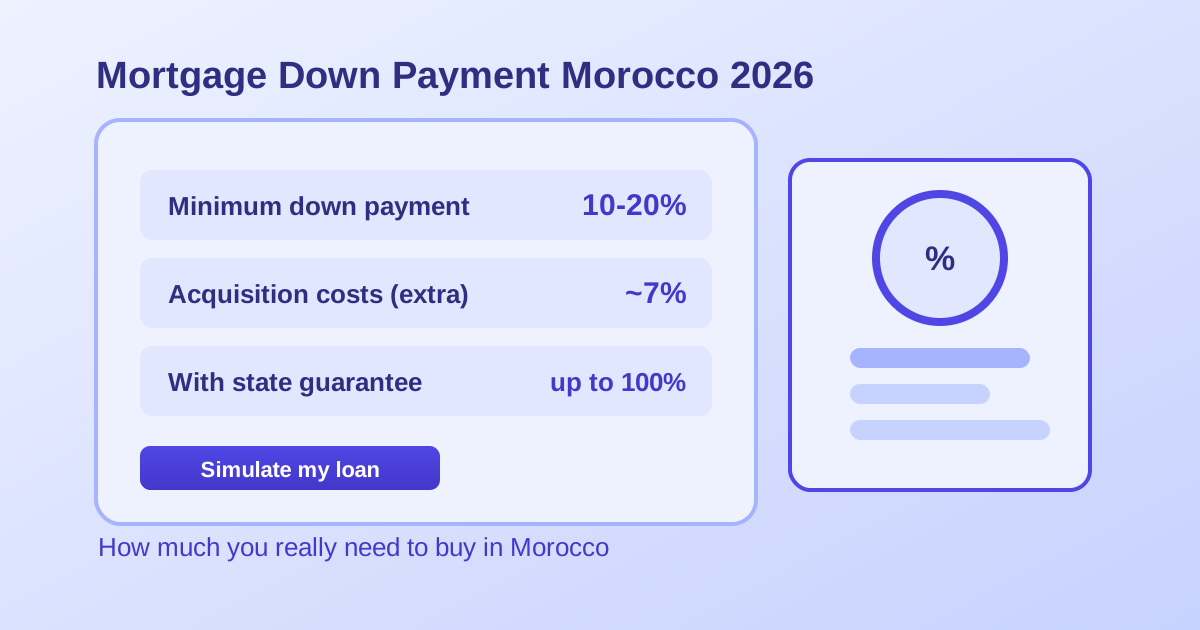
A higher down payment reduces the monthly payment and makes approval easier, but it increases the cash you lock into the deal. The goal is to balance monthly cash flow with return on capital.
If your down payment is too low, the payment can push cash flow negative. If it is too high, ROI declines because you immobilize too much capital. Testing multiple levels is essential.
Use our ROI tool to compare 20%, 30%, and 40% down payments and see the effect on profitability.
Insurance, fees, and total cost of credit
The cost of a mortgage is not just interest. Insurance, file fees, and guarantees add up and can reduce real returns even if the payment looks manageable.
Ask for the full cost breakdown (effective annual rate or equivalent) to compare offers properly. A lower nominal rate can hide higher fees.
In the rental ROI calculator, adjust your monthly expenses to reflect these costs if you want a more complete model.
Exit strategy and flexibility
Before signing, define your exit plan: short-term resale, long-term hold, or shift to short-term rental. The mortgage term should stay aligned with this plan.
Early repayment can be attractive if income rises, but penalties may apply. Read the contract conditions carefully to avoid surprises.
A full simulation in our Morocco ROI calculator helps you anticipate these scenarios and choose the right structure.
Amortization schedule and remaining balance
The amortization schedule shows how payments split between interest and principal. Early in the loan, interest dominates; later, principal repayment accelerates.
This matters if you plan to sell early. A short holding period can leave a high remaining balance, reducing your net proceeds.
Ask the bank for a detailed schedule and compare it with your projections in the calculator.
Renegotiation and refinancing
If rates drop, renegotiating can lower the payment or shorten the term. This can improve cash flow and ROI, but you must compare the fees against expected savings.
Refinancing can also release capital for a new investment, but it increases debt. Use this strategy carefully and stress-test the downside.
Model a new scenario in our ROI tool to see if refinancing improves your position.
Stress test your deal
A strong deal should survive higher rates, lower rent, or a vacancy period. Run these changes to see if you can handle worst-case conditions.
If cash flow becomes heavily negative, renegotiate the purchase price or revise the financing structure before committing.
The rental ROI calculator is ideal for quick stress tests and more confident decisions.
Comparing bank offers effectively
When comparing offers, look beyond the nominal rate. Review total cost, file fees, insurance, and early repayment conditions. Two offers with the same rate can have very different total costs.
Summarize each offer in a simple table so you can see the differences clearly. This helps you avoid hidden costs and choose the best fit for your horizon.
Then simulate each offer in the ROI calculator to see the true impact on cash flow and ROI.
Operational summary
Calculate the payment, then the monthly net cash flow. If the cash flow is positive and stable, the financing is coherent with the rental income.
Add insurance and bank fees, and stress-test higher rates. A strong structure stays viable under conservative scenarios.
Finally, simulate the best offers in the rental ROI calculator and choose the most resilient option.
Final checklist before signing
Confirm your payment, total cost, and early repayment conditions in writing. Do not rely on verbal estimates only.
Make sure the rental assumptions used in your model match real market data from the exact neighborhood.
Run one last test in the ROI calculator with your final loan terms to validate the decision.
Build a monthly safety buffer
Set aside a monthly buffer for maintenance, unexpected repairs, and vacancy. This prevents a temporary issue from turning into a long-term cash flow problem.
A buffer also gives you more flexibility to negotiate, because you are not forced into a deal that only works in perfect conditions.
Stress-test your buffer in the rental ROI calculator and confirm the project remains healthy.
One-minute recap
Focus on payment, total cost, and net cash flow. If those three align, the loan structure is likely solid.
Use conservative rent assumptions and re-run the ROI calculator before signing to avoid last-minute surprises.
Final note
Your financing should support your rental plan, not fight it. If the numbers only work in a perfect case, renegotiate or wait.
Run one last conservative scenario in the calculator and only proceed if the project remains resilient.
Small caution now saves big stress later.
Stay disciplined.
Clarity beats speed.
Avoid rushed decisions.
Patience keeps the plan strong and reduces mistakes later.
Use our Morocco rental profitability calculator
Gratuit · Résultats en 2 minutes