Financing: the central variable of every property project
The financing structure you choose directly determines your monthly payment, monthly cash flow and the final profitability of your investment. A good project on paper can become underperforming if the financial structure is poorly calibrated. In 2026, financing options in Morocco have diversified: classic bank mortgage, Islamic participatory finance (Mourabaha, Ijara) and, for investors with sufficient equity, outright cash purchase.
This guide reviews the main options, their advantages, constraints and key watch points for each profile. Use our mortgage simulator to measure the impact of each financing scenario on your monthly payment and ROI.
How much down payment do you need to buy in Morocco?
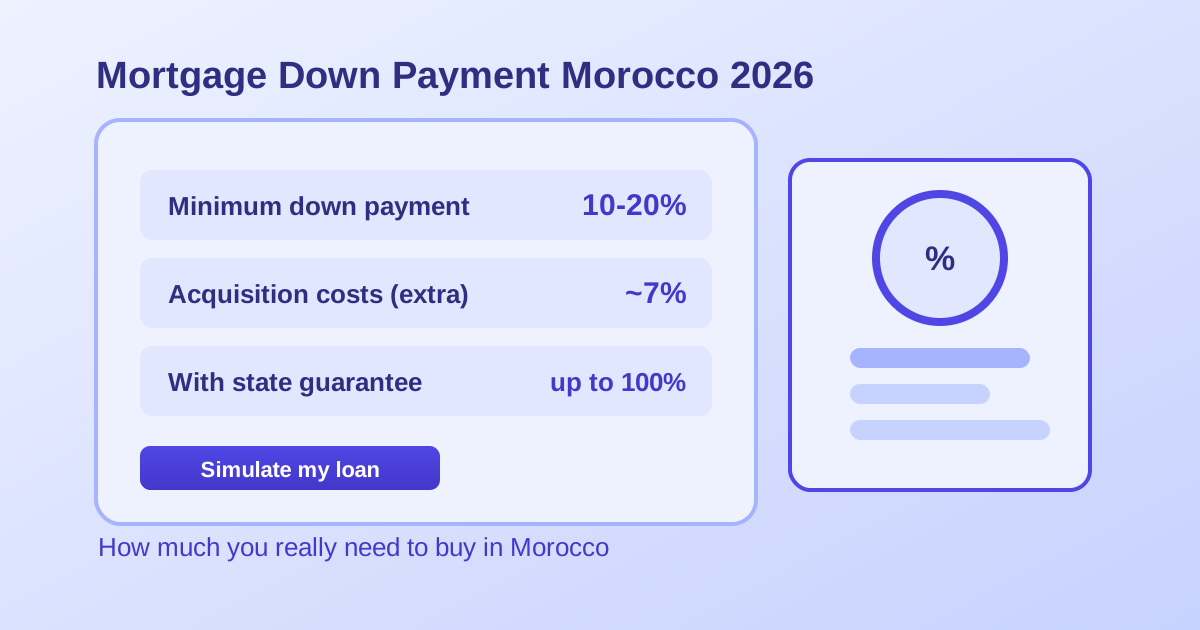
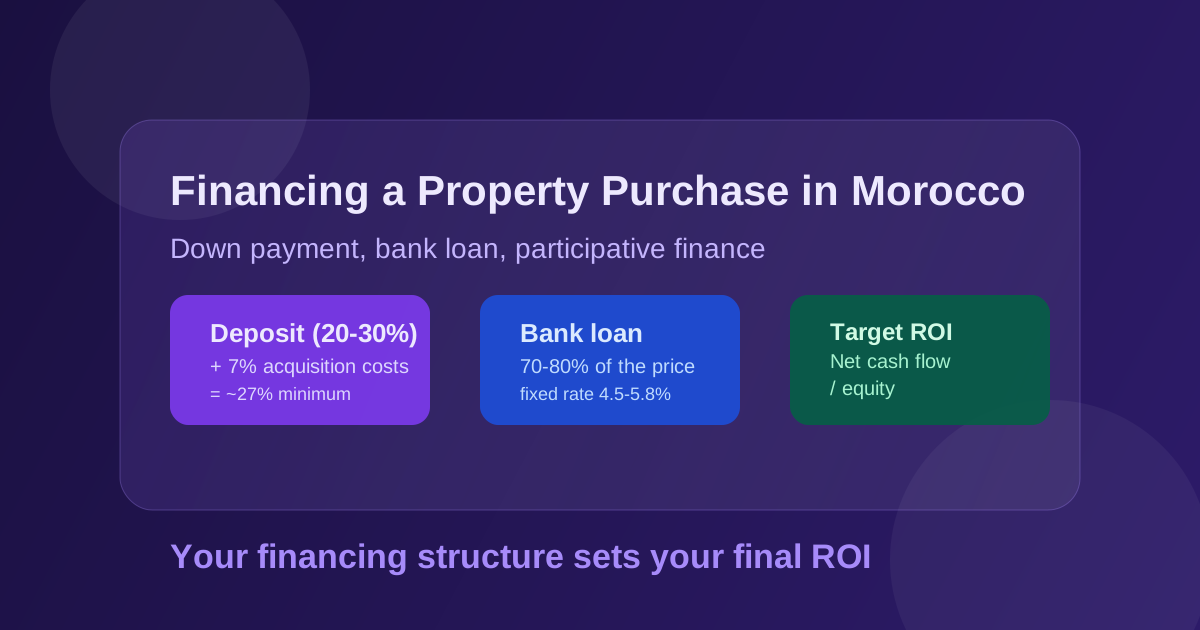
In 2026, Moroccan banks generally require a minimum personal down payment of 20% of the purchase price. On a property at 1,000,000 MAD, that is 200,000 MAD. But the down payment does not cover acquisition costs, which amount to approximately 6.7 to 7% of the price (4% registration duty, 1.5% land registry, ~1.2% notary fees with VAT). For this same property, you need around 270,000 MAD in total personal equity.
A higher down payment (25-30%) reduces the monthly payment, can improve the rate you are offered, and strengthens your application. In return, it ties up more capital. The right level depends on your financial situation and objectives: if you want to preserve liquidity for other investments, 20-25% is often the optimal balance.
For Moroccan residents abroad (MRE), some banks offer specific conditions including foreign-currency financing (euro, dollar), which can be advantageous if your income is in a strong currency. See the acquisition costs guide for a detailed breakdown of all upfront costs.
Classic bank mortgage: conditions and eligibility
The standard bank mortgage remains the most widely used option in Morocco, typically financing 70 to 80% of the purchase price. Eligibility conditions depend primarily on the debt-to-income ratio: total monthly payments (mortgage + other debts) must not exceed 40 to 45% of net income. On 18,000 MAD/month net, the maximum total monthly payments across all debts range from 7,200 to 8,100 MAD.
Professional stability is the second key criterion. Employees on permanent contracts (CDI) with at least 6 months' seniority (ideally one year) at a recognized employer have the best access. Self-employed and liberal professionals can borrow but must demonstrate 3 years of activity and provide 3 complete annual accounts. A clean banking history over the past 12 months (no bounced cheques, no repeated overdrafts) is mandatory.
Our mortgage simulator helps you calculate your monthly payment and identify the maximum you can borrow based on your income.
Participatory finance: Mourabaha and Ijara
Islamic participatory finance is offered by several participatory banks in Morocco (CIH participatif, BTI Bank, Umnia Bank). Mourabaha is the most common formula: the bank purchases the property and resells it to you at a pre-agreed marked-up price, with fixed monthly payments and no conventional interest. Ijara operates on a lease-to-own principle.
The total cost of participatory finance is generally comparable to a classic mortgage, but the structure differs. These products comply with Islamic finance principles and attract a growing share of Moroccan borrowers. Before choosing, compare the total cost (APR equivalent) of both options over the same term and amount using our simulator.
The mortgage application process: key steps
Step 1 - Pre-approval simulation: before visiting properties, get a simulation and pre-approval from 2-3 banks. Provide your last 3 pay slips, 3 months of bank statements, your ID and employment contract. The bank gives you an indicative borrowing capacity in 3 to 7 business days. Step 2 - Preliminary sale agreement and full application: once you have found the property and signed a preliminary agreement, assemble the complete credit file including property documents (land title, ownership certificate). The bank may request an independent property valuation.
Step 3 - Formal offer and acceptance: the bank issues a formal offer which you can accept within 10 days. After acceptance, the bank prepares the funds and coordinates with the notary. Step 4 - Notarial deed and disbursement: the notary convenes both parties to sign the final deed. The bank transfers funds directly to the notary or seller. Acquisition costs are paid simultaneously. The full process from pre-approval to key handover typically takes 6 to 10 weeks under normal conditions.
Borrower insurance and ancillary costs
Borrower insurance (death, total and permanent disability) is mandatory in Morocco for any mortgage. It typically represents 0.2% to 0.45% of the outstanding capital per year. On a 700,000 MAD loan, that is 1,400 to 3,150 MAD/year, or 117 to 263 MAD/month on top of the base monthly payment. Some banks impose their own group policy; others accept external insurance if the guarantees are equivalent.
Bank arrangement fees typically range from 3,000 to 8,000 MAD depending on the institution. Guarantee costs (conventional mortgage charge) can add 1 to 1.5% of the borrowed amount. All these elements must be included in your ROI calculation. Always compare APRs (not just nominal rates) to get the true total financing cost.
How financing impacts investment profitability
Concrete example: property at 1,200,000 MAD, monthly rent 8,500 MAD. Cash purchase: gross yield 8.5%, net yield after charges (~1,500 MAD/month) ~7%. With mortgage: 30% down payment (360,000 MAD) + 7% acquisition costs (84,000 MAD) = 444,000 MAD equity. Loan 840,000 MAD over 20 years at 5.2%, monthly payment ~5,650 MAD. Monthly cash flow: 8,500 - 5,650 - 1,500 = +1,350 MAD/month, or 16,200 MAD/year. Cash-on-cash ROI: 16,200 / 444,000 = ~3.6%.
The mortgage reduces apparent ROI but lets you deploy less personal capital and preserve liquidity for other opportunities. Leverage is positive as long as the asset yield exceeds the financing cost. Test all your scenarios in our ROI calculator before committing.
FAQ + resources on property financing in Morocco
- Can I buy with no down payment in Morocco? Rare and difficult. Banks generally require 20% minimum plus acquisition costs (~7%). Budget at least 27% of the purchase price in personal equity.
- Mourabaha or classic mortgage? Compare total cost over the same term. Choice also depends on your values and profile.
- How long to get a mortgage? Between 6 and 10 weeks typically, from pre-approval to deed signing.
- How do I simulate my financing structure? With our mortgage simulator for the monthly payment and amortization table.
Useful references
Use our Morocco rental profitability calculator
Gratuit · Résultats en 2 minutes