How much down payment do you really need to buy in Morocco?
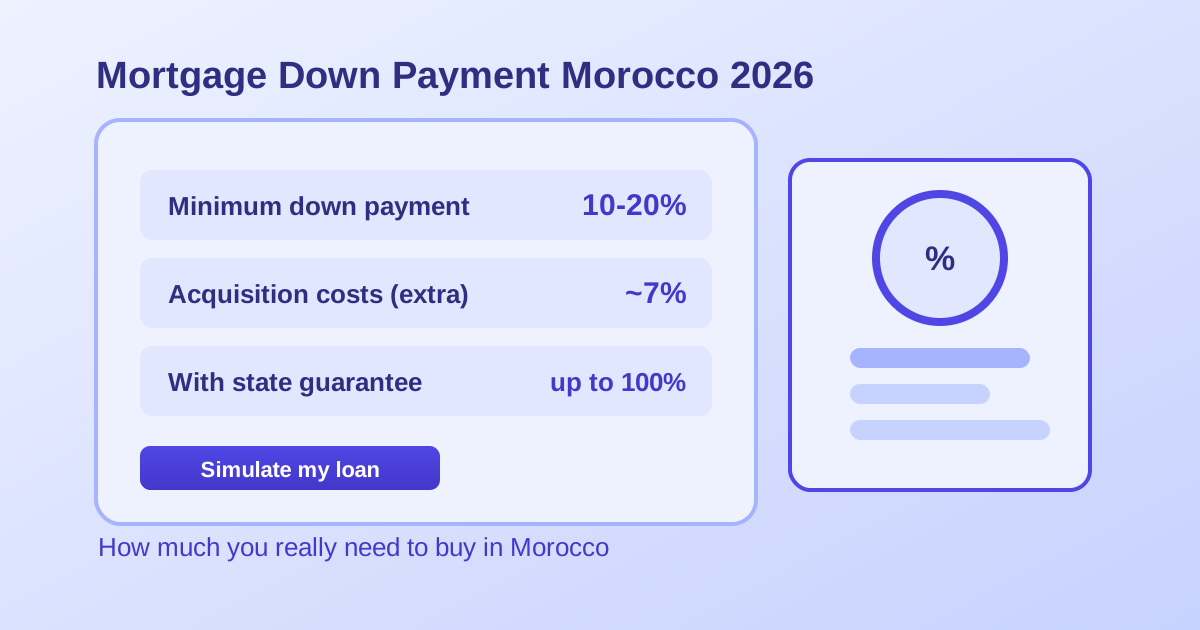
The down payment (apport personnel) is the share of the price you pay yourself, with the rest financed by the loan. In Morocco in 2026, banks generally ask for 10% to 20% of the property price. But the real cash you need is higher, because the acquisition fees (about 7%) are not financed by the loan.
Good news: with state guarantees (Damane Iskan, FOGARIM), financing can reach up to 100% of the cost in some cases. This article details the required percentage, the fee trap, a full worked example, and the schemes that lower the down payment.
The minimum down payment banks require
The standard range is 10% to 20% of the purchase price. Putting 20% down unlocks the best terms: the lowest rates (around 3.9% to 4.25% in mid-2026) are reserved for civil servants and large-company employees who put at least 20% down. A 10% down payment is still possible, often at a slightly higher rate.
Second rule to know: the debt-to-income ratio is capped at 45% of your net monthly income, all charges included (including existing loans). The bank computes the maximum monthly payment from this cap, then works back to the amount it will finance. Test your payment in our mortgage simulator.
The larger your down payment, the less you borrow, the lower your monthly payment, and the stronger your file. The down payment is not just an entry condition: it is a direct lever on the total cost of the loan.
The trap: acquisition fees are not financed
This is the most common mistake. The loan finances part of the property price, but the acquisition fees stay on you, in cash, on top of the down payment. They represent about 6.7% to 7% of the price:
| Item | Rate | On a 1,000,000 MAD property |
|---|---|---|
| Registration duties | 4% | 40,000 MAD |
| Land registry | 1.5% | 15,000 MAD |
| Notary (with VAT) | ~1.2% | ~12,000 MAD |
| Total fees | ~6.7% | ~67,000 MAD |
In other words, the real cash you need at the start is not just the down payment: it is the down payment plus the fees. Many buyers prepare 20% down and discover late that 67,000 MAD of fees is missing. The item-by-item detail is in our acquisition costs guide.
Worked example: a 1,000,000 MAD apartment in Casablanca
Take an apartment at 1,000,000 MAD. With a 20% down payment, you put in 200,000 MAD, plus about 67,000 MAD of acquisition fees. The real cash needed at the start is 267,000 MAD, not 200,000. The loan covers 800,000 MAD.
Over 20 years at 4.5%, the monthly payment on this 800,000 MAD loan comes to about 5,060 MAD.
With a 10% down payment (100,000 MAD), the starting cash drops to 167,000 MAD (down payment + fees), but the loan rises to 900,000 MAD and the monthly payment climbs to about 5,700 MAD. You enter with less cash, but you pay more each month and over the whole term. Compare both setups in the simulator.
Lowering or removing the down payment: state guarantees
The Moroccan state supports access to housing through several schemes that lower the down payment, sometimes to zero:
| Scheme | For whom | Effect on the down payment |
|---|---|---|
| Damane Iskan | Formal income (employees) | 70% guarantee, down payment possible from 10%, up to 100% of cost in some cases |
| FOGARIM | Modest or irregular income, no payslip | 80% guarantee, sharply reduced or zero down payment |
| FOGALOGE | Civil servants | Loan ceiling around 1,000,000 MAD |
| Direct housing subsidy (2024-2028) | First-time buyers | 70,000 to 100,000 MAD depending on the price |
Thanks to the convention between the Ministry of Finance and the Professional Banking Group of Morocco, bank financing can reach 100% of the total acquisition cost for eligible profiles. In practice, a well-built FOGARIM or Damane Iskan file can reduce the down payment to a symbolic amount.
General conditions to check: be of Moroccan nationality, be under 65, and not have already benefited from a state-guaranteed credit. The direct housing subsidy adds on and can serve as a down-payment top-up. These schemes change, so confirm your eligibility with your bank.
How to build your down payment
A down payment can come from your savings, a savings-plan release, a documented family gift, or the sale of a property. For a non-resident Moroccan, transferring foreign currency into a convertible dirham account is a classic source, detailed in our MRE mortgage guide.
Two useful habits. First, do not pour all your savings into the down payment: keep a reserve for fees, any works, and the first few months. Second, keep proof of the source of funds, as the bank may ask for it.
A larger down payment is not always best for a rental investor. If your property generates rent, a smaller down payment increases leverage and the return on equity. Test that trade-off in our profitability calculator.
Mistakes to avoid
Forgetting the acquisition fees in the starting budget is mistake number one. Always plan for the down payment plus 7%.
Borrowing right up to the 45% debt-to-income cap is risky: a payment stretched too tight leaves little room for the unexpected. Aim instead for a comfortable payment, even if it means a larger down payment or a longer term.
Finally, do not overlook the state schemes through lack of information. Many buyers eligible for FOGARIM or Damane Iskan prepare a large down payment when they could finance more. Check before locking up your savings.
Official sources and key takeaways
Key takeaways: plan for a 10% to 20% down payment, plus about 7% of acquisition fees in cash. The debt-to-income ratio is capped at 45% of net income. The Damane Iskan and FOGARIM guarantees can push financing up to 100% of the cost for eligible profiles.
Useful sources
- Bank Al-Maghrib: bkam.ma
- Professional Banking Group of Morocco (GPBM)
- Morocco mortgage simulator
- How to finance a property purchase in Morocco
- Mortgage for non-resident Moroccans
This information is indicative and changes with banks and public schemes. Rates, ceilings and eligibility conditions fall to your bank and the relevant bodies. Have your financing plan validated by an advisor before any commitment.
Frequently asked questions
- What is the minimum down payment for a mortgage in Morocco?
- Banks generally ask for 10% to 20% of the property price. A 20% down payment unlocks the best rates. With state guarantees (Damane Iskan, FOGARIM), financing can reach up to 100% of the cost for eligible profiles.
- Are the acquisition fees included in the loan?
- No. The loan finances part of the property price, but the acquisition fees (about 7%: registration duties 4%, land registry 1.5%, notary ~1.2%) stay on you in cash, on top of the down payment.
- Can you get a mortgage with no down payment in Morocco?
- Yes, in some cases. With FOGARIM (modest or irregular income) or Damane Iskan, financing can cover up to 100% of the acquisition cost. You must be of Moroccan nationality, under 65, and meet the scheme's conditions.
- How much cash do you really need for a 1,000,000 MAD property?
- With a 20% down payment, plan for 200,000 MAD plus about 67,000 MAD of fees, so roughly 267,000 MAD of cash at the start. With 10% down, about 167,000 MAD, but a higher monthly payment.
- What is the maximum debt-to-income ratio accepted?
- The debt-to-income ratio is capped at 45% of net monthly income, all charges included, including existing loans. The bank works back from it to the maximum monthly payment, and from there to the amount it will finance.
Use our Morocco rental profitability calculator
Gratuit · Résultats en 2 minutes